Recover your password
Enter your email that you login with, for the instructions to be sent to your registered email.
Sign in
Reset Password

You can also sign in using your account in one of the social networks.


Create account for free and enjoy unlimited access to exclusive industry insights and reports

Create a New Account
  • News
  • Insights
  • Companies
    Companies Database Companies Ranking
  • Market Reports
  • Tools & Resources
    Infographics Announcements
  • Pricing
Logo
  • Halal Industry
  • Islamic Finance
  • Islamic Lifestyle
  • OIC Economies
Sign In Create Account

Sign In Create Account

  • Halal Industry
  • Islamic Finance
  • Islamic Lifestyle
  • OIC Economies

  • PREMIUM REPORTS
  • News
  • Insights
  • Companies
    Companies Database Companies Ranking
  • Market Reports
  • Tools & Resources
    • Infographics
    • Events and Courses
    • Announcements


Home / Insights

Featured Insights

Islamic Finance

The future of money: Understanding the CBDC revolution

13 Nov 2026
Insight

Islamic Finance
Explainer: How embedded finance can reshape the Islamic financial landscape
05 Oct 2026
Insight

Islamic Finance
How Islamic social finance is keeping Sudan alive
01 Oct 2026
Insight

Islamic Finance
What is Islamic Finance?
22 Sep 2026
Insight

Islamic Finance
Sponsored
AAOIFI Shariah Standard 62: A hexagonal fiqhi-market synthesis
22 Jun 2026
Insight

Islamic Finance
Sponsored
GDP-linked Sukuk: A tool for economic growth and stability
02 Jun 2026
Insight


All Other Insights
Islamic Finance
The future of money: Understanding the CBDC revolution

For the longest time, central banks held the head seat for being policy makers and regulators - sentinels over all things financial. They drafted the rulebook and enforced it. Understandably, their efforts came in for high praise, too. 

But the world since has changed. In all its entirety, some may argue. Governments can no longer function as administrators alone; in a world dominated by digital wallets, encrypted keys, tokenisation, ledger technology and of course, AI, it would be remiss of them to view themselves as mere gatekeepers. It is therefore essential for regulators to also become shapers of behaviours and markets – agile, collaborative and if required, avant-garde. 

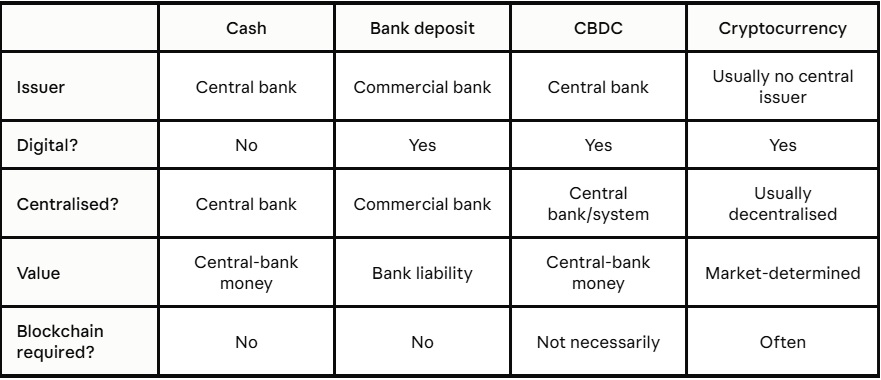
This was perhaps the spirit behind the notion of Central Banks considering their own digital currencies. So, what is a central bank digital currency (CBDC)? It is digital money issued by the central bank. Similar to how cash is a physical claim on the central bank, a CBDC is a claim in digital form. 

Until now, financial institutions could hold deposits with central banks; CBDCs aims to extend this facility to retail and corporate customers. 

But is a CBDC essentially a cryptocurrency issued by the central bank? Not quite because it does not require a distributed ledger technology to run it. A cryptocurrency, such as a bitcoin, runs on blockchain technology, is privately created and decentralized. That no central authority maintains absolute dominion is perhaps its core essence. Its value can fluctuate, too. 

Here is where a CBDC differs: The digital currency would be centrally issued and recorded, backed by a central bank and would essentially carry the same security as cash. More so, it is denominated in the country’s existing currency. 

So, if the Bank of England issued a digital pound, it would not be a new currency in the same sense Bitcoin is. It would be another form of sterling. More importantly, a CBDC is not dependent on blockchain technology, it could simply use a conventional centralised database. 

“A CBDC is money issued by the central bank and owed by it, in the same way banknotes are. The system used to record who owns it is a separate design choice,” says Dr Najmul Haque Kawsar, senior consultant at DinarStandard. 

“Bitcoin uses a blockchain because no single person or institution is trusted to keep the record, so many computers keep it together. A central bank is already the trusted record-keeper for a country's money. It can choose a distributed ledger when that suits its goals, as the UAE did, or a central database when transaction volume matters most, as China did.”

Integration or transformation: Rethinking the ecosystem
The world has been slow to adapt to CBDCs. There are 41 CBDC pilot projects around the world out of the 146 countries monitored by the Atlantic Council’s CBDC tracker. Three countries - the Bahamas, Jamaica, and Nigeria - have fully launched a central bank digital currency. All 11 BRICS members are exploring a CBDC, with nine members already in the pilot phase and Egypt and Ethiopia in research. 

However, the larger economic question in the current context is not record keeping or its purpose. It essentially lies in the integration of digital money with - and interdependence on - commercial banks and their enduring role in the existing monetary system?

“The prevailing model is two-tier: the central bank issues the currency, and licensed institutions distribute it and keep the customer relationship. The UAE's Digital Dirham follows this approach, with licensed financial institutions distributing it to users through digital wallets. The European Parliament's position likewise sees private banks as the main distributors of the digital euro, with the ECB setting the holding limit within a ceiling agreed by EU institutions,” Faysal A. Ghauri, managing partner and chief strategist at FANUUN Business Consulting Group, tells Salaam Gateway. 

The Atlantic Council's 2025 research found that most countries prefer the two-tier design, where people access the CBDC through banks or fintechs.

“This [intermediated design] keeps the fractional banking model in place. Under that model, a bank holds a portion of its customers' deposits in reserve and lends out the rest. Because banks stay in the middle, deposits can keep flowing through them and keep funding loans,” says Kawsar. 

“For the UAE or Malaysia, the digital dirham or ringgit upgrades existing payment infrastructure, and most of the change happens behind the scenes. Today, many payments between banks are settled in batches. Transactions are grouped and cleared at set times. The digital dirham or ringgit moves this to real-time atomic settlement. The transfer and the final settlement happen in a single step, and if any part of the transaction fails, the whole transaction is cancelled.”

How is a CBDC different to money in a bank account?
How is a central bank issued digital money any different to funds in a customer’s bank account? Isn’t most of the world’s money circulating in modern economies digital anyway? 

A CBDC transfers liability ownership from a commercial bank to the state coffer. If a customer has $1 in Bank X, it is a deposit liability of the aforementioned bank. Bank X owes that customer $1. But if the same customer has $1 of a CBDC, it would be a direct liability of the central bank. Customers could feel more at ease with the latter option, but this could trigger disintermediation on a broader level.

“Banks will distribute the CBDC through their own apps and digital wallets. That puts them in a difficult position though. For example, a customer who moves 10,000 dirhams from a current account into digital dirham. That money leaves the bank's balance sheet and becomes a direct claim on the central bank, held in the customer's CBDC wallet. Banks will only distribute the CBDC willingly if the central bank gives them something in return. How the central bank designs those incentives, while protecting the deposit and lending model, will decide whether the rollout works,” says Kawsar.  

“The ECB's own simulations indicate that a EUR 3,000 holding limit could trigger withdrawals of up to EUR 699 billion from eurozone banks, equivalent to 8.2% of retail sight deposits, with a disproportionate effect on smaller lenders,” adds Ghauri.

Does it get trickier for Islamic lenders?
Islamic banks face a sharper version of the problem, according to Ghauri.

“For Islamic finance markets there is a further structural challenge. Interest-based liquidity tools, such as the interbank market, the discount window and the lender of last resort, are not permissible for Islamic banks, and Islamic liquidity instruments remain slow to develop.”

An IMF study of conventional and Islamic banking systems revealed that the risk of bank disintermediation in jurisdictions with Islamic banks is further heightened by the predominance of retail deposits in bank funding.
“Islamic banks face a specific version of the deposit problem,” adds Kawsar.

“Many structure their current accounts as qard, an interest-free loan from the customer to the bank, which pays no contractual return. If a CBDC also pays no return, customers have one less reason to keep money in those accounts.” 

13 Nov 2026
Insight
Islamic Finance
Explainer: How embedded finance can reshape the Islamic financial landscape

The importance of embedded finance cannot be overstated. It not only broadens the market by making Islamic finance more relevant, but also enables banks to serve geographically dispersed customers more efficiently.

We speak with Mike Breen, chief commercial officer, audax, on how embedded finance can open new customer segments for Islamic banks, and the verticals where he views the next big opportunity for embedded offerings.

Islamic finance assets are estimated to hit $9.7 trillion by 2029, yet you've pointed to a growing "distribution gap." Can you unpack what's driving it?

Breen: Customers are increasingly moving between digital platforms and ecosystems for different parts of their everyday lives, and they expect financial services to fit naturally into those journeys. Yet banking products are still largely distributed as a separate, bank-owned experience that customers have to seek out.

For banks, that represents an untapped growth opportunity. As Islamic finance grows, the opportunity is not only to expand the products available, but to broaden how customers access them. This is why we believe the next phase of digitalisation needs to not only focus on building better digital banking capabilities, but also on extending those capabilities through new distribution models that reach a wider range of customers.

AmanahPro embeds a Shariah-compliant Hajj savings account directly into MuslimPro rather than a standalone banking app. Why is that distribution model more effective?
Breen:
Meeting customers within a platform they already use gives banks access to an established audience and an existing customer relationship, rather than asking them to start anew. It also allows financial products to be introduced at a point where they are relevant to what the customer is trying to do.

AmanahPro demonstrates this in practice. Saving for Hajj is not simply a standalone financial transaction; it involves putting money aside through multiple transactions over time. This makes it an ongoing financial need that can form part of a customer’s preparations for Hajj. This complements, rather than replaces, bank-owned channels. 

While AmanahPro is focused on the Indonesian market, this model is directly relevant to banks in the Middle East and other mature Islamic finance markets and can be applied to regional ecosystems across the GCC and beyond, with local banks and partners. 

How do you see embedded finance opening up new customer segments for Islamic banks — particularly younger, digitally native consumers?
Breen:
Younger customers may not necessarily begin by looking for an Islamic banking relationship, but they will encounter needs around saving, payments, travel, education, financing or investing. 

Embedded finance allows banks to introduce a Shariah-compliant solution around that specific need, rather than asking the customer to buy into a broader banking proposition upfront. That also gives Islamic banks a different way to build relevance with a generation whose financial relationships may be more fragmented. A customer may use different platforms for payments, investing, commerce or travel rather than relying on one bank for everything. 

Islamic finance has traditionally centered on the Middle East and Southeast Asia. What needs to happen — technologically and structurally — for it to scale into newer markets?
Breen:
Islamic finance is now present across 98 countries, with 84 non-OIC countries either expressing interest in or already active in the industry as of 2024. Its appeal is also broadening beyond Muslim consumers, yet the industry remains highly concentrated, with Iran, Saudi Arabia and Malaysia accounting for 72% of global Islamic finance assets. 

Technologically, banks need infrastructure that makes expansion portable rather than bespoke. New products, customer journeys and partnerships should be able to sit on top of existing core systems, allowing banks to enter or test a new market without rebuilding the underlying stack each time. 

Structurally, that portability has to be matched by the ability to localize. Regulatory requirements and Shariah governance can vary significantly by market, so controls, oversight and security need to be designed in from the outset rather than added later. This gives banks the flexibility to adapt propositions to local requirements and work with new ecosystem partners.

You've spoken about "trust by design." How can banks and ecosystem partners collaborate on embedded offerings without compromising Shariah governance or transparency?
Breen:
The global embedded finance market was valued at $145.03 billion in 2025. As more financial services are delivered through third-party ecosystems at this scale, the cost of getting governance wrong becomes much greater — not only in terms of regulatory and operational risk, but also the potential erosion of customer trust. 

For Islamic finance, where Shariah compliance is fundamental to the integrity of the product, embedded finance should change how and where that product is delivered, but not the standards of governance and transparency behind it.

Modern banking infrastructure is what allows these responsibilities and controls to be maintained across the ecosystem. Banks can build an engagement and orchestration layer on top of their existing systems to securely extend banking capabilities into partner ecosystems without replacing the underlying core. 

Within this layer, customer journeys, workflows and integrations can be managed alongside embedded security and regulatory controls, including governed access to data and banking capabilities, secure third-party integrations, and monitoring and auditability. 

Where does audax see the next big opportunity for embedded Islamic finance?
Breen:
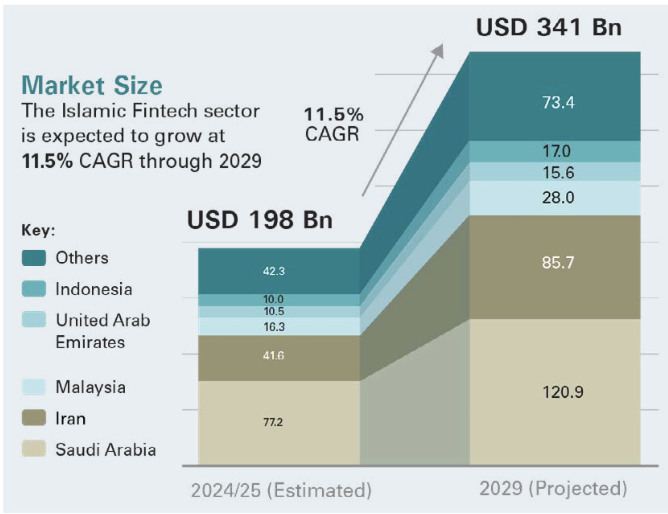
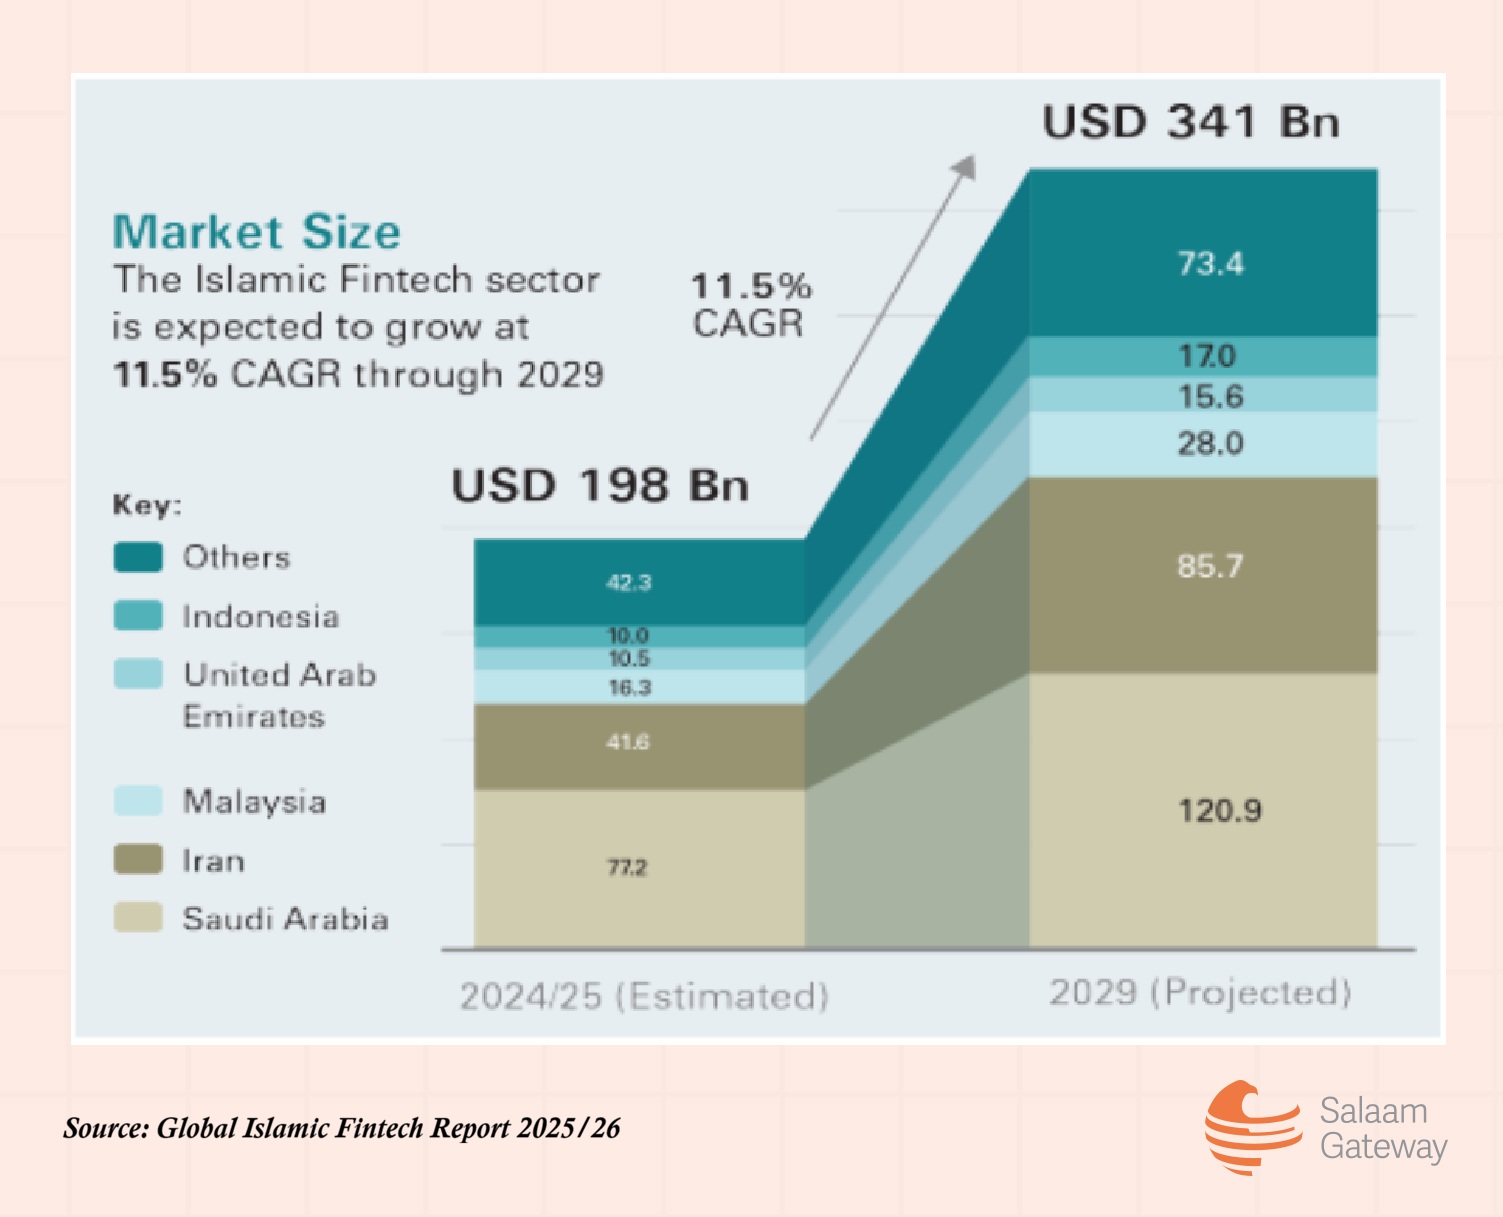
For audax, the next opportunity lies at the convergence of new verticals, new markets, and the right ecosystem partners. Global Islamic fintech transaction volumes are projected to reach $341 billion by 2029 - In our view, driving that growth will require both expanding access in emerging markets and modernising how Islamic financial services are delivered in more established ones. 

In Southeast Asia, through our partnership with Maybank Islamic, our focus is on enabling modern, customer-centric Islamic banking capabilities across the bank’s priority markets, including Indonesia, Malaysia and Singapore, as well as emerging markets such as the Philippines. 

These markets are at different stages of Islamic finance development. Malaysia and Indonesia have well-established Islamic finance sectors, while the Philippines presents a different opportunity centred on expanding access. 

Beyond Southeast Asia, the Middle East, and the UAE in particular, is also a core market for audax. Through our existing partnership with Tuum, we are broadening our modernisation proposition for financial institutions across the region.

The next phase is about bringing the elements together: modernising the underlying banking capabilities, extending them into relevant ecosystems and deploying them across priority markets where there is meaningful demand. 

05 Oct 2026
Insight
Islamic Finance
How Islamic social finance is keeping Sudan alive

As international humanitarian aid falls dangerously short, Muslim diaspora networks are stepping in to sustain food, healthcare, and community support across Sudan     

The sheer scale of Sudan’s humanitarian crisis defies comprehension. 

According to the World Health Organization, 33.7 million people require urgent assistance, 21.2 million face acute food insecurity, and 11.5 million have been forcibly displaced.

But the reality behind these numbers is starker: Parents skipping meals to feed their children, families trekking for days to find refuge, and neighbors keeping community kitchens alive while artillery fire echoes through their neighborhoods.

“It’s families who are simply trying to get a meal for today and can’t even think about what they’ll have to eat tomorrow,” says Michael Selby-Green, international media coordinator at Islamic Relief, a UK-headquartered non-profit organisation. 

Testimonies reveal harrowing details - some have told Islamic Relief they are surviving on leaves and animal feed for lack of everything else. 
     
When civil war erupted in April 2023, the mechanisms of state-led relief crumbled almost overnight. Compounding this failure is a glaring shortfall in global support. The UN’s humanitarian response for Sudan barely met 40% of its funding targets in 2025, stripping traditional aid safeguards from the world’s largest displacement and hunger crisis.

Now, three years into the conflict, Islamic social finance tools such as Zakat, Sadaqah, as well as Muslim diaspora networks are helping fill some of the gaps left by faltering international support.

Geography of hunger and siege

The crisis looks dramatically different depending on where people reside     .

In parts of Darfur and North and West Kordofan, the risk of famine remains acute. Elsewhere, fighting has eased enough for some displaced civilians to return home. But returning home does not necessarily mean returning to normal life.

“Return reads as a positive indicator in most datasets. On the ground it’s a new caseload,” says Khan.

In Darfur, people are confronting siege-like conditions.

When Penny Appeal Canada operated a central kitchen in Abu-Shouk Camp in El-Fasher, North Darfur last October, the local market had effectively stopped functioning.

“We could not run normal competitive procurement, so funds went directly to the kitchen supervisor to buy whatever was physically available that day,” says Khan.

Volunteers cooked and delivered meals with persistent shelling. Shortly after the project closed, Penny Appeal Canada lost contact with many of the camp committees. 

Some displaced families later reached the Northern State. At Al-Afad Camp in Al-Dabbah, the organisation provided daily iftar to 600 households in early 2026.

“One man there had walked four days to reach it,” says Khan.

When food becomes privilege      

Sudan’s hunger crisis is not just about whether food is physically available.

In some areas, markets continue to operate, but inflation, currency depreciation and disrupted supply chains have pushed prices beyond the reach of ordinary households.

“Even where food is available in markets, the lack of physical cash means people can’t always buy it, and prices have become unaffordable to most people because of massive inflation and supply shortages,” says Selby-Green.

This is one reason Muslim Hands, an international NGO in over 52 countries, has increasingly prioritised emergency food assistance, hot meals, and cash-based support alongside its longer-established seasonal food programmes. 

Penny Appeal Canada describes the situation as “price volatility rather than absolute scarcity”.

“Food exists. Households cannot afford it and agencies cannot budget against it,” Firaz Khan, the organisation’s programs communications specialist tells Salaam Gateway.

The power of Islamic charitable giving

Sudan’s community kitchens, known as Takaaya, have become a vital grassroots response to hunger. 

Islamic Relief works with some of these kitchens and has called for greater international support. Hundreds have faced closure over the past year, according to the organisation, with many relying heavily on donations from Sudanese communities abroad.

“Zakat and other similar types of donations are crucial for Islamic Relief’s response in Sudan and have become even more so since governments around the world cut aid over the last few years,” says Selby-Green.

Zakat is an obligatory annual charity for every qualifying adult Muslim whose wealth exceeds a specific threshold. Sadaqah, meanwhile, is a voluntary act of giving done out of compassion, with no fixed amount or timeline.

At the Zakat Foundation of America (ZFA), funding comes primarily from individual community donors through Zakat and Sadaqah. 

“In Sudan, these contributions translate into food, healthcare, shelter, essential household supplies and assistance for vulnerable children and families,” a ZFA spokesperson tells Salaam Gateway. 

The foundation says it has worked in Sudan since 2007 and that its emergency response since April 2023 has reached nearly 167,000 people.

For Penny Appeal Canada, faith-based giving accounts for most of its Sudan portfolio. “It’s not one stream among several. For Sudan it’s close to the whole thing,” says Khan.

Zakat, Zakat al-Fitr, Qurbani and Sadaqah from Canadian Muslim donors fund the organisation’s work. During Ramadan 2026, Zakat al-Fitr reached 2,000 families in the Khartoum State, while Qurbani, a ritual sacrifice of livestock during Eid Al Adha, provided fresh meat to communities where protein was otherwise unaffordable.

The challenge of seasonality and security 

For all the charitable tools available, emergency food support can not rely solely or indefinitely on Islamic philanthropy, due to the seasonality of donations and the longevity of assistance required.           

Sudan was historically a major agricultural producer, but the destruction of farms, displacement of farmers, looting of machinery, and collapse of markets have damaged the foundations of food security.

Islamic Relief is therefore combining urgent relief with livelihood programmes to reduce dependence on emergency aid as families regain the ability to produce food and earn an income.

“Emergency relief saves lives, but it isn’t a long-term solution,” says Selby-Green. “Farmers need seeds, tools, fertiliser, cash, and support to rehabilitate irrigation systems, including solar systems.”

The seasonality of Islamic charitable donations compounds the issue. “The trade-off is timing,” says Khan. “Zakat and Qurbani concentrate liquidity into Ramadan and Dhul Hijjah. Emergencies do not.”

For Sudan, the challenge is turning Muslim generosity into a reliable, year-round lifeline. More so, this generosity needs to be channelled through accountable structures. 

Penny Appeal Canada operates entirely through Sudanese partners, who undergo due diligence before funds are transferred, while beneficiary lists are verified in the field. Because displaced families are constantly on the move, these lists must remain “live.”

Similarly, Muslim Hands has relied on community-based organisations to extend its reach. Since April 2023, its programs have reached nearly 350,000 people, delivering food, clean water, education, and emergency response.

“Local organisations provide much more than logistical support,” Faisal Safdar, manager of global operations development at Muslim Hands tells Salaam Gateway.

A prime example is the NGO’s work with the Alryada Voluntary Organization, whose insight enabled targeted assistance for displaced families in Atbara, Aldamer, and Shandi, cities located in the River Nile State of Sudan. 

“This has helped us reach highly vulnerable demographics, including female-headed households, people with disabilities, and individuals living with chronic illnesses,” Safdar notes.
01 Oct 2026
Insight
Islamic Finance
What is Islamic Finance?

Islamic finance is an alternative financial system based on Islamic law, more commonly referred to as Shariah. 

The doctrine governs how money can be raised, invested, lent, and borrowed, with real economic activity at the heart of all dealings, alongside ethical conduct and fairness.

The key principles are:
•    Prohibition of Riba or interest: Money cannot generate a guaranteed return only because it was lent out to a party that needed it. 
•    Avoidance of excessive uncertainty: Contracts and transactions should be sufficiently clear and transparent. 
•    Prohibition of gambling: Transactions based primarily on gambling or chance are prohibited. 
•    Shariah-compliant investments: Financing and investment should avoid prohibited sectors and activities. 
•    Asset or transaction backing: Islamic financial structures are based on an underlying asset, trade or business activity.


The common Islamic finance products include Sukuk, Islamic funds, Islamic deposits, home finance and trade finance. 

•    Sukuk: Certificates representing interest or an ownership share in a tangible asset, project or an investment activity.
•    Islamic funds: Funds investing in Shariah-compliant assets
•    Islamic deposits: Deposits structured to generate returns through Shariah-compliant contracts.
•    Home finance: Financing through Shariah-compliant contracts such as diminishing Musharakah, Ijarah or Murabaha rather than interest-bearing mortgages.
 

The underlying Shariah contracts or structures on which Islamic finance products can be built are as follows: 

  • Murabaha: Cost-plus sale in which the seller discloses the acquisition cost and profit margin.
  • Musharakah: Partnership in which the parties contribute capital and share profits and losses.
  • Mudarabah: Partnership in which one party contributes the capital while the other manages the investment.
  • Ijarah: Lease in which the lessor provides the right to use an asset in return for rental payments.
  • Wakalah: Agency arrangement in which one party appoints another to act on its behalf.
22 Sep 2026
Insight
Islamic Finance
AAOIFI Shariah Standard 62: A hexagonal fiqhi-market synthesis

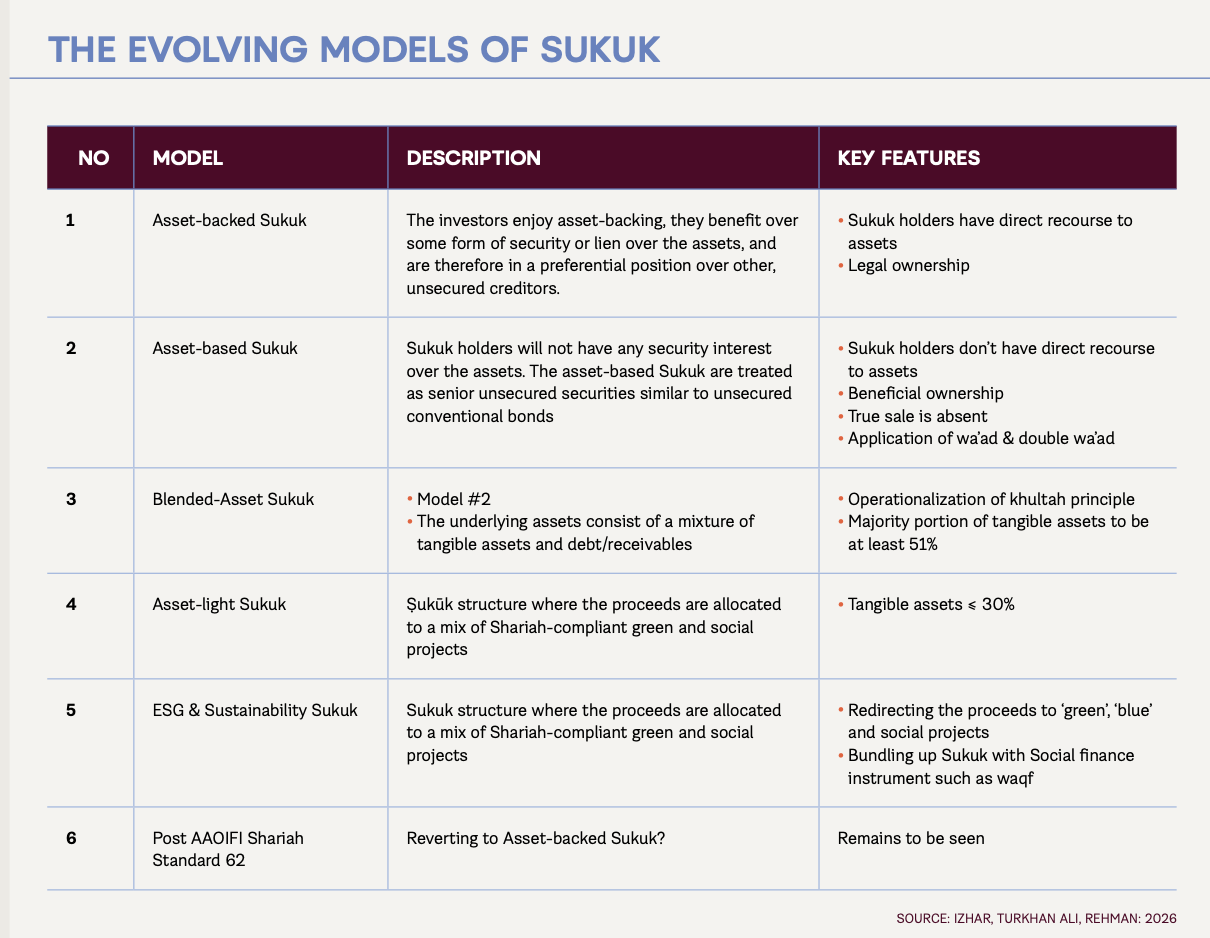
The global sukuk market has undergone significant structural evolution since its modern inception, adapting to investor appetites, regulatory frameworks, and market dynamics while navigating persistent tensions between Shariah authenticity and financial functionality and adapting to the changing needs and dynamics of the global financial market and stakeholder appetites. The following evolutionary depiction, adapted from Yagci, Izhar, and Turkhan Ali (2025), traces this trajectory:

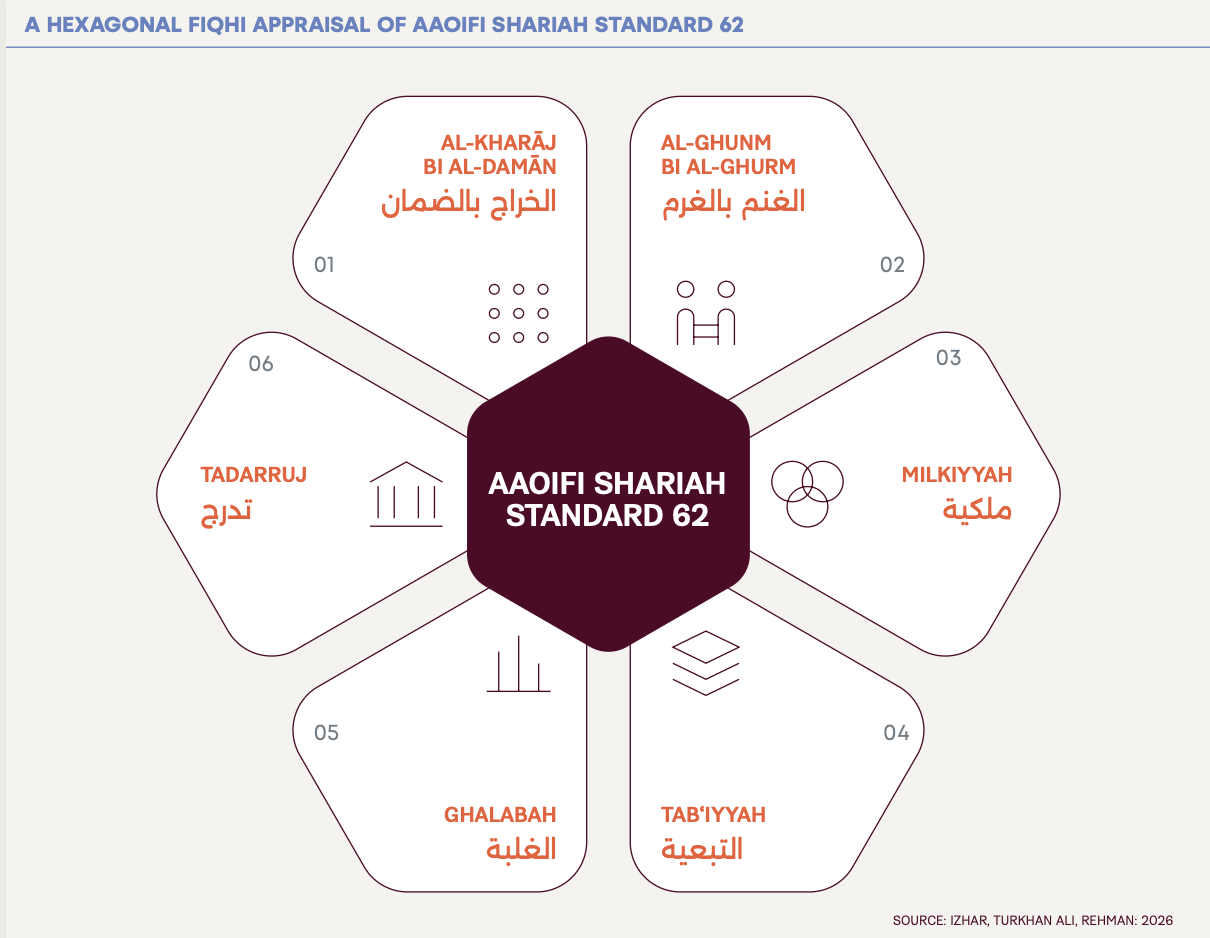
AAOIFI Shariah Standard 62 (SS62) represents a pivotal development in the evolution of the global  sukūk market. At its core, the standard seeks to address a long-standing structural imbalance—namely, the pre-dominance of asset-based sukuk structures that grant investors only beneficial ownership rather than the asset-backed arrangements grounded in genuine ownership and effective risk transfer. While this corrective shift is firmly anchored in classical Shariah principles, its implications for contemporary financial markets are significant and potentially far-reaching.

By requiring substantive ownership and the assumption of risk, SS62 realigns sukuk structures with foundational Shariah maxims such as al-ghunm bi al-ghurm and al-kharāj bi al-ḍamān. The standard also carries important implications for tradability, placing greater emphasis on the actual composition and nature of underlying asset pools rather than relying solely on numerical thresholds or ratios. In doing so, it reinforces the legitimacy of jurisprudential approaches where ownership and risk-bearing are genuine and substantive.


In response to these developments, the Islamic Development Bank Institute has conceptualized two complementary institutional mechanisms: the Ṣukūk Development Finance Corporation (DFC) and the Ṣukūk Enhancement Fund (SEF). The DFC is designed to issue asset-backed sukuk to finance development projects while avoiding the need for governments to transfer strategic public assets. The SEF, in turn, functions as a mutual risk-sharing platform among issuers, strengthening credit quality and improving pricing without reliance on external guarantees.

Together, these mechanisms provide a practical pathway for the gradual transition toward SS62-compliant sukuk structures. While the DFC facilitates the large-scale issuance of asset-backed sukuk for sovereign and development financing, the SEF mitigates systemic risk and expands access to authentic sukuk for smaller issuers, including SMEs. Collectively, they offer scalable institutional solutions capable of supporting the implementation of AAOIFI SS62 while minimizing disruption to existing market dynamics.


Dr. Hylmun Izhar is a Senior Research Economist at the Islamic Development Bank Institute (IsDBI). Dr. Turkhan Ali Abdul Manap is a Senior Research Economist at IsDBI. Yahya Rehman is Associate Manager, Knowledge Leaders Section, at IsDBI.

22 Jun 2026
Insight
Islamic Finance
GDP-linked Sukuk: A tool for economic growth and stability

This article is produced and sponsored by IsDBI. It was first published in the State of the Global Islamic Economy 2025/26 report produced by DinarStandard. The report can be downloaded from here.


I.    Introduction 
The alarming rise in global public debt demands innovative, long-term financing solutions. For the Global South, the “Looming Debt Crisis” highlights the need for transformative approaches beyond temporary relief. Among these, GDP-linked bonds are emerging as a promising pathway for sustainable development financing. 

First proposed in the 1980s and gaining renewed support after successive debt crises, GDP-linked debt aligns repayment with economic performance. Supported by leading economists and the IMF, this model offers a sustainable way to manage debt and promote sustainable growth. 

Islamic finance principles, rooted in risk-sharing, make GDP-linked Sukuk a natural fit for development finance. By tying obligations to GDP, these Sukuk provide equitable and resilient solutions that align with Islamic ethics. 

This article explores the potential value of this model and the role of blockchain technology in supporting implementation. Blockchain ensures secure and transparent tracking of economic data, while smart contracts enhance the efficiency of execution. 

II.    Structure 

The coupon and principal in GDP-linked bonds rise and fall in proportion to the issuing country’s nominal GDP. Robert Shiller has called these instruments “GDP shares” as they allow governments to raise funds while linking repayments to the resources of the economy. In this model, sovereign obligations adjust in line with economic performance.

Shiller has argued that replacing part of conventional national debt with claims linked to economic output could help governments better manage financial obligations, reduce the risk of future crises, and potentially lower borrowing costs over time.

Interest in the indexing of debt servicing to GDP first emerged in the 1980s and received fresh support after frequent debt crises. The idea was supported by several distinguished economists, including Joseph Stiglitz and has also received favorable consideration from the IMF. 

III.    Features 

In their Foreword to the book Sovereign GDP-Linked Bonds: Rationale and Design (2018), Andy Haldane of the Bank of England and Maurice Obstfeld of the IMF, note the following appealing features of GDP-linked bonds: 

  • They can provide the issuing government with debt relief when growth weakens and tax receipts decline. 
  • Investors gain a route out of being locked into low-interest rates through exposure to the real economy while the debt-stabilizing effects of issuance mean default risks become more remote. 
  • They also allow risk to be shared across borders more efficiently, ultimately reducing the need for sovereign bailouts and limiting moral hazard. 

The “automatic stabilizer” role of GDP-linked instruments reduces the need to resort to procyclical policies. When economic growth slows, GDP indexation can ease debt pressures, lower the probability of default, and help reduce financial distress and rising unemployment. 

In periods of low GDP growth, the GDP-linked instruments can reduce debt-servicing costs and reduce the need for more borrowing or taxes. This would help to smooth the tax rate and reduce uncertainty for consumption and investment. Conversely, higher payments during stronger GDP growth may discourage governmental overspending. As a result, sovereigns may gain greater short-term budget flexibility while maintaining long-term solvency and resilience to financial turmoil.

A key element for the success of GDP-linked bonds, Griffith-Jones remarks is to identify the proper set of investors interested in this kind of bond. Given their equity-like features, they may appeal to equity investors as well as those interested in hybrid instruments. Moreover, since GDP-linked bonds are directly linked to the overall economy, they have elements of Development Impact Bonds. 

Arshadur Rahman of the Bank of England suggests issuing GDP-linked Sukuk. To the extent that GDP is correlated with government income, then the GDP-linked Sukuk will represent a form of partnership between the government and investors. From a Shari’ah perspective, this structure potentially emulates musharakah arrangements. 

IV.    Blockchain networks 

A serious challenge for GDP-linked instruments is the reliability of the data on which investors’ returns depend. Conventional economic statistics rely on samples intended to represent the entire economy, but these may create inaccuracies requiring revision in subsequent releases. In addition, given the centralized nature of the process, data are exposed to the risks of manipulation and interference. These challenges limit the appeal of GDP-linked instruments to investors. 

Issuing GDP-linked papers requires establishing an effective system for collecting verifiable and consistent data. Blockchain technology can be very helpful in this regard. This can be done as follows: 

1.    A group of blockchain networks of consumers, producers, wholesalers, and retailers, among others, can be established with the verifiable identities of each member of each network. Each network would be dedicated to a particular sector of the economy.  


2.    Data from sector-specific networks can be aggregated into a national blockchain network, providing a comprehensive and real-time estimate of GDP. 


3.    This unified approach ensures consistency and avoids duplication or gaps in data collection. 


4.    Members of each network could report: 
a.    Current price of a pre-identified set of goods and services within their respective sectors.  
b.    Expected prices over defined future periods. 

5.    Reported data are verified by members following blockchain verification and consensus algorithms. The IsDB Institute developed the patented “Proof of Use” algorithm as a more economically sustainable alternative to Proof of Work. 

6.    Members could be rewarded tokens issued by the networks’ sponsors such as the central banks or relevant authorities. 

This process would help ensure that the collected data are transparent, observable, easy to compute, and non-manipulative. Since the technology requires only an internet connection and smartphones, the data collection process requires minimal upfront costs. 

The Blockchain network can be used to collect various kinds of data including indicators related to financial inclusion and broader development outcomes. 

Digital GDP-linked Sukuk could be issued and distributed through the Blockchain network. These Digital Sukuks would represent a tokenized form of the Sukuk certificates and their underlying contractual terms.  

Smart contracts can be used to link the periodic Sukuk payments with the data collection network. Using blockchain on both sides, data collection and Sukuk issuance are likely to make the entire process seamless, transparent, and efficient. This allows the Sukuk to be accessible to a wider range of investors, particularly retail investors. 

V.    Issues and challenges 

While the Digital GDP-linked Sukuk might be conceptually appealing, there are many issues that need to be addressed before implementation. For example: 

  • Managing the blockchain networks would be demanding and may involve some centralized control. Although the risks of manipulation are much lower than the centralized approach, some risks remain. 
  • Developing countries, which stand to benefit most from GDP-linked Sukuk, may face challenges in implementing and maintaining blockchain networks due to limited infrastructure and technical expertise. 
  • Ensuring that all economic actors, including those in remote or underserved areas, can participate in the blockchain network will require extensive outreach and capacity building. 
  • GDP-linked Sukuk are suitable for most middle-income countries with promising growth prospects. 
  • Very-low-income countries could issue sector-specific Sukuk tied to growth in sectors such as agriculture, mining, or oil & gas. 
  • Although the GDP-linked Sukuk of a single country may carry higher risk, a diversified portfolio of such instruments could reduce risks. 

VI.    Conclusion 
Islamic finance is, at its core, a risk-sharing system with the capacity to absorb and manage various economic risks. This will not make the economy risk-free, but it will make these risks manageable and self-stabilizing. However, when debt becomes excessive, these risks can become destabilising. 

GDP-linked Sukuk offers an innovative approach to sustainable financing by aligning debt obligations with a country's economic performance. This instrument can help curb excessive debt accumulation while promoting a more stable and inclusive growth, reflecting the risk-sharing principles of Islamic finance.  

Author: Dr. Sami Al Suwailem Acting Director General, IsDBI


This article is produced and sponsored by IsDBI. It was first published in the State of the Global Islamic Economy 2025/26 report produced by DinarStandard. The report can be downloaded from here.

© State of the Global Islamic Economy 2025/26 All Rights Reserved


02 Jun 2026
Insight
Islamic Finance
UAE’s sovereign financial cloud aims to safeguard more than just data  

The UAE Central Bank’s initiative to build a sovereign cloud platform for the country’s financial institutions goes beyond data residency, according to experts. 

The AI-powered sovereign financial cloud service infrastructure, which will function on an isolated yet centralized architecture, is designed to ensure the continuous availability of critical financial services for the local financial sector. 

“Sovereign financial clouds are designed to protect the financial system itself, not just the data inside it,” Matt Kaluzny, a cloud & data architect tells Salaam Gateway.

“The objective of sovereign financial clouds is to combine the scale and maturity of global cloud platforms with national control over sensitive financial infrastructure.”

Operated by Core42, a subsidiary of Abu Dhabi technology group G42, the platform will ensure data sovereignty and integrity, isolating it from global outages, cyber threats and geopolitical disruptions.  Embedded real-time analytics and AI monitoring will add an additional layer, driving intelligent automation, deeper operational insights and better decision making. 

A sovereign cloud is a cloud computing service curated to store and process data in compliance with local laws and security standards.

“Sovereign cloud is a cloud ecosystem that ensures complete control over data, infrastructure, and operations, free from external jurisdictional influence, and aligned with local regulatory, technical, and operational requirements,” Manish Ranjan, research director for software & cloud at International Data Corporation tells Salaam Gateway. 

Western hyperscalers such as Amazon Web Services (AWS), Oracle and Microsoft have substantial presence on ground, operating assets across the UAE. AWS launched its Middle East (UAE) region in 2022, which includes three availability zones housing one or more data centres; Oracle and Microsoft both run multiple cloud regions, including data centres in the country. 

The key difference between the two configurations lies in its jurisdictional control and focus. For instance, AWS cloud is sovereign-by-design, offering controls that permit customers to meet their sovereignty requirements, but a sovereign cloud is a purpose-built, isolated environment, operating under state’s oversight and control. 

“Global providers such as AWS already support UAE rules on data location, privacy, and assurance and are widely used by banks. By embedding security guardrails, automated policy checks, and reporting, [the sovereign financial cloud] minimises compliance overhead and accelerates deployment. Banks still retain architectural and operational control of their applications and data, but they benefit from a more standardized, regulator aligned environment,” says Ranjan. 

Centralizing governance, localizing control
Lijo Joseph, IT project manager at Pru Life UK says that what makes this significant is the idea of introducing regulatory oversight directly into financial infrastructure. 

“Today, many financial institutions operate with different cloud environments, different security controls, different compliance interpretations. Instead of every bank solving compliance independently, governance becomes part of the platform itself,” explains Joseph. 

Core42’s broader sovereign cloud strategy is publicly centred around a multi-year partnership with Microsoft, but whether the sovereign financial cloud will leverage the hyperscale capabilities of the alliance remains unclear. 

“Core42 has a long-standing partnership with Microsoft and already operates large-scale AI and cloud platforms using Azure technology. It is therefore likely that elements of this partnership will support parts of the sovereign financial cloud infrastructure. However, in sovereign cloud models, the key question is not only which hyperscaler technology is used, but who governs the environment and controls the critical security layers,” adds Kaluzny. 

“While the cloud may leverage global hyperscaler technologies, operational control remains local. This means that critical elements such as security tooling, access policies, and encryption key management are administered within the UAE under national regulatory oversight. The sovereign operator controls how the infrastructure is configured, monitored, and governed, while hyperscaler platforms provide the underlying technology stack.” 

What is clear in no uncertain terms is that it will rev up innovation and ingenious solutions through the platform.

The sovereign financial cloud platform will potentially drive innovation more than a general purpose cloud, says Ranjan, with a sector specific sovereign platform creating a shared digital foundation across banks, allowing them to experiment, co-develop, and scale solutions. 

“However, it is critical to ensure this platform supports modern cloud native tooling and open standards,” he adds, “so it doesn’t slow down the pace of innovation that the financial sector now expects.”

23 Mar 2026
Insight
Islamic Finance
Top 10 Islamic fintech ecosystems in 2025

Islamic fintech has emerged in recent times as one of the fastest-expanding segments of the financial technology sector. Yet, despite its growth, it still accounts for only about 1.5% of the global fintech market, suggesting enormous expansion potential in the years ahead. As regulators refine frameworks and venture capital flows into the sector, the countries that combine strong Islamic finance foundations with digital innovation are likely to shape the next generation of ethical finance.

According to the Global Islamic Fintech Report 2025/26, the sector reached $198 billion in transaction volume and assets under management in 2024/25, and is projected to grow to $341 billion by 2029, representing an 11.5% compound annual growth rate (CAGR).

At the same time, the global Islamic fintech ecosystem has expanded to 484 companies worldwide, spanning digital payments, alternative finance, wealth management, crowdfunding, and tokenised assets.

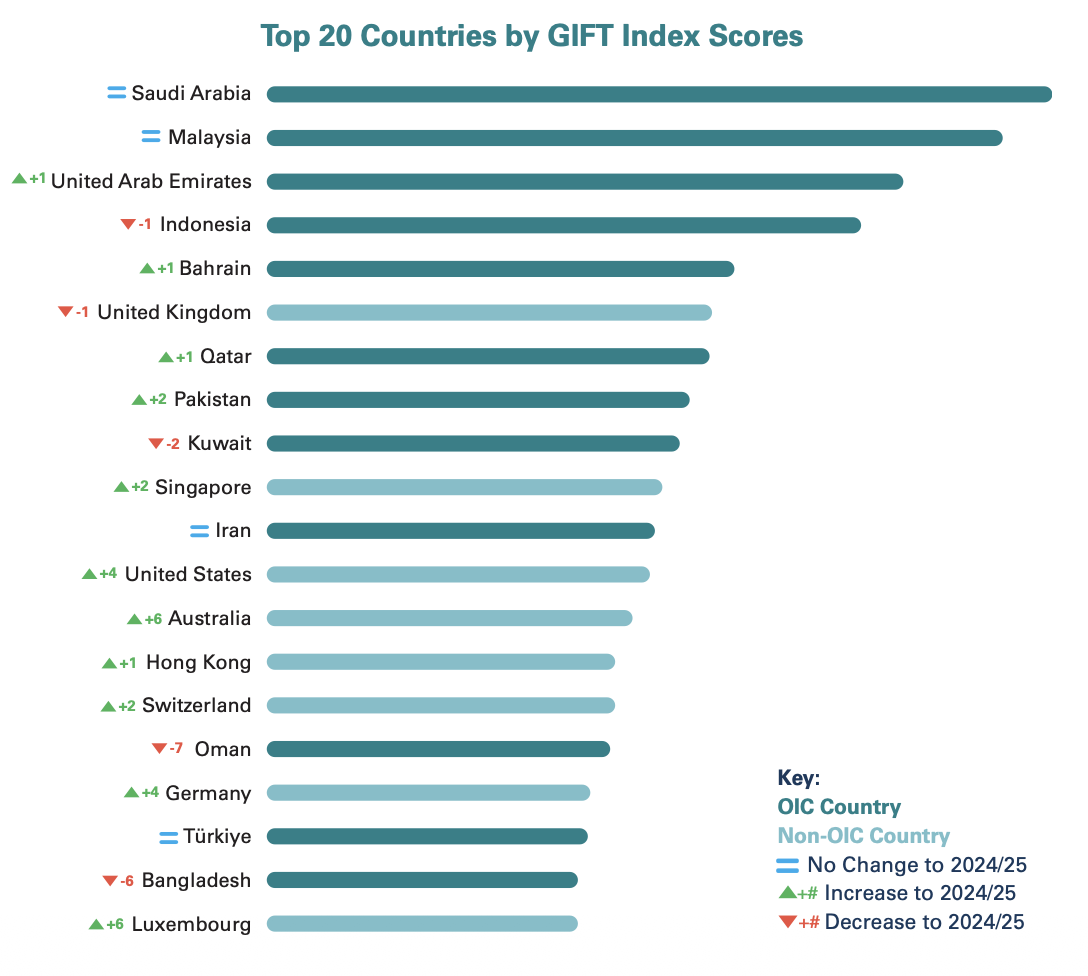
To understand which countries are leading this transformation, the report compiled the Global Islamic Fintech (GIFT) Index, a benchmarking framework covering 64 countries and measuring ecosystem strength across regulation, talent, infrastructure, capital, and market depth.

Below are the 10 strongest Islamic fintech ecosystems in the world today, ranked by their GIFT Index scores.

1. Saudi Arabia
GIFT Index Score: 84.2
The Kingdom hosts 74 Islamic fintech firms, the largest national cluster in the world. Saudi Arabia benefits from one of the largest Islamic finance markets in the world and strong government backing through Vision 2030. Digital banking licenses, open banking regulations, and fintech sandboxes have accelerated growth across payments, lending, and digital asset platforms.

2. Malaysia
GIFT Index Score: 79.1
Malaysia’s long-standing leadership in Islamic banking and sukuk markets provides a natural foundation for fintech innovation. Recent initiatives such as asset tokenisation frameworks and digital banking licenses continue to strengthen its ecosystem.

3. United Arab Emirates
GIFT Index Score: 68.0
The UAE ranks third, with 55 Islamic fintech companies, and is active in payments, digital assets, and investment platforms. Dubai and Abu Dhabi have established fintech sandboxes, regulatory innovation hubs, and tokenisation initiatives, positioning the UAE as one of the most active regulatory environments for Islamic fintech experimentation.

4. Indonesia
GIFT Index Score: 63.0
Indonesia has 58 Islamic fintech companies, reflecting the scale of its domestic market and its large Muslim population. Indonesia’s fintech ecosystem is particularly active in peer-to-peer lending, digital payments, and crowdfunding platforms designed for underserved consumers and SMEs.

5. Bahrain
GIFT Index Score: 49.2
Bahrain rounds out the top five with a GIFT Index score of 49.2. Although its domestic market is smaller, Bahrain has long been an early mover in Islamic finance regulation. The country’s fintech regulatory sandbox and digital banking frameworks have helped it remain influential despite its size.

6. United Kingdom
GIFT Index Score: 46.5
The United Kingdom ranks sixth globally, the highest-ranking non-OIC jurisdiction. The country is home to 52 Islamic fintech firms, reflecting London’s position as a global financial hub. Islamic fintech activity in the UK focuses heavily on digital investment platforms, crowdfunding, and ethical finance solutions, supported by the country’s advanced fintech infrastructure.

7. Qatar
GIFT Index Score: 46.2
Qatar hosts 22 Islamic fintech companies, supported by initiatives such as the Qatar Financial Centre fintech ecosystem and digital asset labs. It’s strategy focuses on regulatory clarity and financial infrastructure to attract startups and international partnerships.

8. Pakistan
GIFT Index Score: 44.2
Pakistan enters the Top 10 for the first time and hosts 19 Islamic fintech companies, reflecting rapid growth in mobile payments and digital banking. Pakistan’s expanding Islamic banking sector and large unbanked population have created fertile ground for fintech innovation.

9. Kuwait
GIFT Index Score: 43.0
Kuwait’s strong Islamic banking sector provides the foundation for fintech innovation, particularly in digital payments, investment platforms, and SME financing solutions.

10. Singapore
GIFT Index Score: 40.8
Although not traditionally an Islamic finance hub, Singapore rounds out the top 10. The country hosts 14 Islamic fintech firms, benefiting from its global fintech ecosystem and strong regulatory clarity. Its role is increasingly that of an international bridge connecting Islamic fintech startups with global capital markets.

Methodology 
This ranking evaluates 64 countries using 19 indicators grouped into five core categories:
• Talent
• Regulation
• Infrastructure
• Islamic Fintech Market & Ecosystem
• Capital

Each indicator is first normalised using a min-max methodology, allowing different data types to be compared on the same scale. Category scores are then calculated and weighted to produce a final composite score for each country. The Islamic Fintech Market & Ecosystem category receives the highest weighting, reflecting the importance of real market activity, such as the number of fintech firms and Islamic financial institutions.

Limitations
While the GIFT Index offers the most comprehensive benchmarking framework available, several constraints remain:

  • Data availability: Islamic fintech activity is not always reported consistently across countries.
  • Proxy-based market estimates: Market size estimates sometimes rely on Islamic banking market share as a proxy for fintech activity.
  • Rapid regulatory change: Digital asset regulations and fintech policies evolve quickly, meaning ecosystem strength can shift rapidly.
07 Mar 2026
Insight
Islamic Finance
Venture capital and Islamic fintech: underfunded or unscalable?

Islamic fintech does not lack narrative or ambition.

There are two billion potential Muslim customers globally. Islamic finance assets exceed $6 trillion. Markets across the GCC and Southeast Asia combine strong banking penetration with rising digital adoption. Diaspora markets like the UK remain structurally underserved.

The Global Islamic Fintech Report 2025/26 estimates the size of Islamic fintech at $198 billion, projected to reach $341 billion by 2029. There are 484 Islamic fintech firms worldwide, concentrated largely in alternative finance, wealth management, payments, deposits and lending. Digital assets, takaful and social finance remain less developed but show momentum.

Yet despite these tailwinds, Islamic fintech still represents just 1.5% of the global fintech market.

The opportunity and growth are clear, but capital remains selective.

Not always a venture case
Venture capital is often the first route founders consider when raising funding. But Abdul Haseeb Basit, co-founder and principal of Elipses, suggests the sector needs to think more carefully about fit.

“Mostly, Islamic finance products require patience and development. They don't have the same turnaround times as conventional venture investments, so it requires a type of patient capital that perhaps isn't venture capital.”

Islamic finance is rooted in asset-backing, risk-sharing and structured governance. That does not always align neatly with venture capital’s expectation of rapid scaling and defined exit timelines.

Hazem Ben-Gacem, founder and chief executive of BlueFive Capital, agrees that venture capital is only one tool. His firm led Mal’s $230 million seed round, backing what it describes as the world’s first AI-native Islamic digital bank. The investment demonstrates that institutional capital is prepared to move at scale when conviction is strong.

“VC works well for high-growth, scalable platforms, which is why we led this round for Mal,” he says. “But Islamic finance is fundamentally rooted in asset-backing, risk-sharing and ethical allocation of capital. That aligns more naturally with revenue-based financing, sukuk, or even crowdfunding in certain contexts. We need a hybrid approach.”

Wahed offers another example. The US-based Islamic robo advisory platform has raised multiple rounds to expand across the US, UK and MENA markets. Licensing friction did not deter investors because the underlying business model scaled and governance structures were clear.

These examples show Islamic fintech can attract venture funding. The issue is that only specific models fit the venture profile.

Going beyond faith positioning
Islamic fintech combines digital infrastructure with principles such as asset-backing, transparency and risk-sharing. Shariah compliance matters to customers. Investors, however, assess propositions differently.

Khalid Howladar, managing partner at advisory and venture firm Acreditus, argues that targeting underserved Muslim communities can be commercially logical at the outset.

“As long as your project can make money serving this segment, venture capital will follow,” he says.

However, Howladar adds a crucial caveat. “Focusing on community is not enough. Just being Islamic is not enough. You need to be solving a problem, ensuring product market fit.”

Basit echoes this point. He believes founders need to broaden their lens. “Most of the development today has been around structuring the products in a Shariah-compliant way. Now the focus needs to shift to their merits as an investment product more holistically.”

To scale, Islamic fintech must demonstrate that it delivers better financial outcomes, not simply compliant alternatives.

The firms attracting capital tend to compete on commercial fundamentals first, with Shariah embedded in governance rather than positioned as the sole differentiator.

Product diversity and scalability
The Global Islamic Fintech Report highlights the heavy concentration of firms in retail-facing segments such as payments and wealth management. These areas are important but can be geographically constrained and highly competitive.

Greater product diversity is needed, such as digital asset rails aligned with asset-backing principles; capital markets technology; embedded Islamic finance within broader ecosystems; SME financing platforms with scalable underwriting models. These types of propositions are more likely to scale across markets and attract institutional capital.

Ben-Gacem argues Islamic fintech remains underfunded relative to its structural opportunity.

“The challenge has been twofold,” he says. “First, many solutions have been reactive - digitising conventional Islamic products rather than reimagining them. Second, the investor base has been too narrow. We see this as a gap in perception, not performance. What’s been missing is conviction at scale.”

Investors have shown greater willingness to back regulated infrastructure than narrowly positioned consumer applications. That distinction is likely to shape future deal flow.

A shallow capital escalator
Even where early-stage capital exists, scaling remains uneven.

Basit describes what he calls a weaker “capital escalator”. Incubators and angel networks are active. However, later-stage funding remains limited. 

He notes that corporate venture participation from Islamic banks is not yet widespread, and IPO pathways for high-growth technology firms in many OIC markets are still developing.

Without visible late stage exits, institutional LPs hesitate to allocate capital to specialised Islamic fintech funds. Without larger funds, scaling beyond Series A or B becomes difficult.

“There needs to be a whole-of-ecosystem approach when it comes to funding a company from inception to exit,” adds Basit. 

“We haven't seen much later-stage scaling. We have seen some exits, for example CoinMENA was a trade sale. That is probably likely to be the most common outcome for most Islamic fintechs.”

Governance and interpretation risk
Another friction point lies at the intersection of Shariah governance and venture structuring.

Amjad Hussain, partner at law firm K&L Gates in Qatar, notes that founders sometimes focus on Shariah compliance at the product level while relying on conventional funding instruments at the equity level.

“Early funding continues to be raised through conventional instruments that are drafted in a debt-like or return-protective nature,” he says. “Convertible notes, for example, are typically framed as debt that converts into equity and often include an interest component, which is an obvious friction point in a Shariah context.”

Hussain argues that Shariah governance should be embedded from the outset, with “instrument choice, conversion mechanics and investor protections aligned from the first term sheet”.

At the same time, he cautions against overcorrecting.

“The aim is not to reinvent venture economics, but to express them in equity-forward terms that are commercially familiar and Shariah-compliant.”

Consistency is key
Islamic fintech benefits from favourable structural trends. Demand is robust. Regulatory clarity in markets such as Malaysia and parts of the GCC is improving.

But venture capital is not unlocked by narrative alone. It requires scalable business models, disciplined governance, predictable regulatory planning and credible exit pathways.

Islamic fintech has demonstrated that capital can be raised. The challenge is not promoting an outlier. It is making it the norm. 

02 Mar 2026
Insight
View all Insights

Reports
PLUS State of the Global Islamic Economy (SGIE) 2025/26 Report
28 Jun 2026

Building Payment Rails for 2 Billion People
06 May 2026

PLUS Global Islamic Fintech Report 2025/26
18 Feb 2026

View all reports

Announcements
Rakbank Islamic enables access to Bitcoin trading through its Islamic banking platform

24 Aug 2026


Madinah Angels closes investment into Kestrl, a UK-based, values-driven fintech helping Muslims and ethical consumers manage their money in accordance with their beliefs

28 Jul 2026


Dubai Residential REIT’s landmark listing named “Best IPO in the Middle East” by EMEA Finance

24 Jun 2026


View all announcements

Subscribe to our newsletter

Get Islamic economy and Halal Industry updates in your inbox

By submitting this form you are acknowledging that you have read and agree to our privacy statement


Infographics
Halal Industry
Top 10 halal food ecosystems in the world
08 Oct 2026

View all

Events & Courses
View all

Special Coverage

Top 30 Business Schools of the Islamic Economy 2026

View all

30 Notable Islamic Fintechs - 2026

View all

30 Notable Islamic Fintechs - 2025

View all

Global Islamic Fintech Report 2025/26

View all

15 Most Active VCs in the Islamic Digital Economy

View all

State of the Global Islamic Economy (SGIE) 2024/25 Report

View all

Global Islamic Fintech Report 2024/25

View all

Top 30 Digital Islamic Economy Startups 2024

View all

Top 30 OIC Halal Products Companies 2023

View all

Gaza Crisis

View all

Global Islamic Fintech Report 2023/24

View all

The State of the Global Islamic Economy 2023/24 Report

View all

Global Islamic Fintech Report 2022

View all

State of the Global Islamic Economy 2022

View all

Food Security

View all

Women in the Islamic Economy

View all

COVID-19 and the Global Islamic Economy

View all

E-book: Impacts of the COVID-19 outbreak on Islamic finance in OIC countries

View all

State of the Global Islamic Economy 2020/21

View all

Global Islamic Fintech Report 2021

View all
A note from Salaam Gateway

We're growing — and want you to be part of our journey

Salaam Gateway has always been your home for independent, in-depth coverage of the global Islamic economy. To help us go deeper and do more, we're introducing a membership tier for our premium reports and insights — so we can produce more of everything you've come to love.

With your free account, you get:
  • 5 full articles every month
  • Full access to our Lists & Rankings
  • Executive summaries of our premium reports
  • Our weekly Islamic-economy newsletter
No card required. No catch. Just good journalism.
Explore membership
List Your Company

Create your company profile on Salaam Gateway to reach a global Islamic audience.

Create
Publish Your Announcement

Share your company's latest updates.

Submit
Share Your Event or Course

Reach thousands of Islamic economy businesses and professionals.

Add
Logo
Follow
  • Halal Industry
  • Islamic Finance
  • Islamic Lifestyle
  • OIC Economies
  • Market Reports
  • News
  • Insights
  • Companies
  • Infographics
  • Announcements
  • Cookies Policy
  • Privacy Statement
  • Terms of Use
  • About us
  • Contact us

© 2026 Salaam Gateway