For the longest time, central banks held the head seat for being policy makers and regulators - sentinels over all things financial. They drafted the rulebook and enforced it. Understandably, their efforts came in for high praise, too.
But the world since has changed. In all its entirety, some may argue. Governments can no longer function as administrators alone; in a world dominated by digital wallets, encrypted keys, tokenisation, ledger technology and of course, AI, it would be remiss of them to view themselves as mere gatekeepers. It is therefore essential for regulators to also become shapers of behaviours and markets – agile, collaborative and if required, avant-garde.
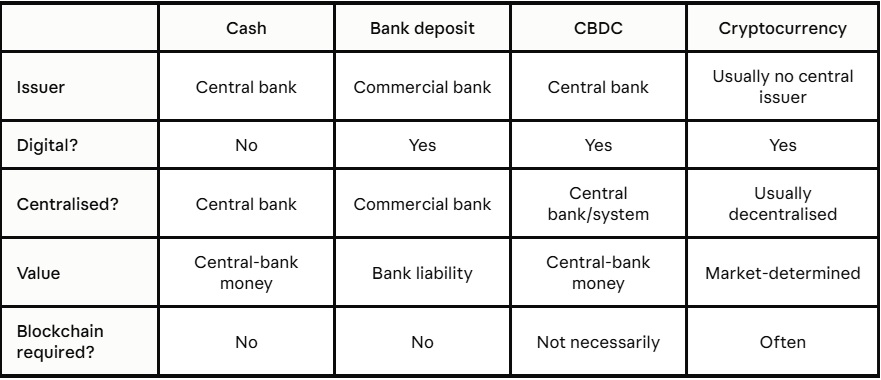
This was perhaps the spirit behind the notion of Central Banks considering their own digital currencies. So, what is a central bank digital currency (CBDC)? It is digital money issued by the central bank. Similar to how cash is a physical claim on the central bank, a CBDC is a claim in digital form.
Until now, financial institutions could hold deposits with central banks; CBDCs aims to extend this facility to retail and corporate customers.
But is a CBDC essentially a cryptocurrency issued by the central bank? Not quite because it does not require a distributed ledger technology to run it. A cryptocurrency, such as a bitcoin, runs on blockchain technology, is privately created and decentralized. That no central authority maintains absolute dominion is perhaps its core essence. Its value can fluctuate, too.
Here is where a CBDC differs: The digital currency would be centrally issued and recorded, backed by a central bank and would essentially carry the same security as cash. More so, it is denominated in the country’s existing currency.
So, if the Bank of England issued a digital pound, it would not be a new currency in the same sense Bitcoin is. It would be another form of sterling. More importantly, a CBDC is not dependent on blockchain technology, it could simply use a conventional centralised database.
“A CBDC is money issued by the central bank and owed by it, in the same way banknotes are. The system used to record who owns it is a separate design choice,” says Dr Najmul Haque Kawsar, senior consultant at DinarStandard.
“Bitcoin uses a blockchain because no single person or institution is trusted to keep the record, so many computers keep it together. A central bank is already the trusted record-keeper for a country's money. It can choose a distributed ledger when that suits its goals, as the UAE did, or a central database when transaction volume matters most, as China did.”
Integration or transformation: Rethinking the ecosystem
The world has been slow to adapt to CBDCs. There are 41 CBDC pilot projects around the world out of the 146 countries monitored by the Atlantic Council’s CBDC tracker. Three countries - the Bahamas, Jamaica, and Nigeria - have fully launched a central bank digital currency. All 11 BRICS members are exploring a CBDC, with nine members already in the pilot phase and Egypt and Ethiopia in research.
However, the larger economic question in the current context is not record keeping or its purpose. It essentially lies in the integration of digital money with - and interdependence on - commercial banks and their enduring role in the existing monetary system?
“The prevailing model is two-tier: the central bank issues the currency, and licensed institutions distribute it and keep the customer relationship. The UAE's Digital Dirham follows this approach, with licensed financial institutions distributing it to users through digital wallets. The European Parliament's position likewise sees private banks as the main distributors of the digital euro, with the ECB setting the holding limit within a ceiling agreed by EU institutions,” Faysal A. Ghauri, managing partner and chief strategist at FANUUN Business Consulting Group, tells Salaam Gateway.
The Atlantic Council's 2025 research found that most countries prefer the two-tier design, where people access the CBDC through banks or fintechs.
“This [intermediated design] keeps the fractional banking model in place. Under that model, a bank holds a portion of its customers' deposits in reserve and lends out the rest. Because banks stay in the middle, deposits can keep flowing through them and keep funding loans,” says Kawsar.
“For the UAE or Malaysia, the digital dirham or ringgit upgrades existing payment infrastructure, and most of the change happens behind the scenes. Today, many payments between banks are settled in batches. Transactions are grouped and cleared at set times. The digital dirham or ringgit moves this to real-time atomic settlement. The transfer and the final settlement happen in a single step, and if any part of the transaction fails, the whole transaction is cancelled.”
How is a CBDC different to money in a bank account?
How is a central bank issued digital money any different to funds in a customer’s bank account? Isn’t most of the world’s money circulating in modern economies digital anyway?
A CBDC transfers liability ownership from a commercial bank to the state coffer. If a customer has $1 in Bank X, it is a deposit liability of the aforementioned bank. Bank X owes that customer $1. But if the same customer has $1 of a CBDC, it would be a direct liability of the central bank. Customers could feel more at ease with the latter option, but this could trigger disintermediation on a broader level.
“Banks will distribute the CBDC through their own apps and digital wallets. That puts them in a difficult position though. For example, a customer who moves 10,000 dirhams from a current account into digital dirham. That money leaves the bank's balance sheet and becomes a direct claim on the central bank, held in the customer's CBDC wallet. Banks will only distribute the CBDC willingly if the central bank gives them something in return. How the central bank designs those incentives, while protecting the deposit and lending model, will decide whether the rollout works,” says Kawsar.
“The ECB's own simulations indicate that a EUR 3,000 holding limit could trigger withdrawals of up to EUR 699 billion from eurozone banks, equivalent to 8.2% of retail sight deposits, with a disproportionate effect on smaller lenders,” adds Ghauri.
Does it get trickier for Islamic lenders?
Islamic banks face a sharper version of the problem, according to Ghauri.
“For Islamic finance markets there is a further structural challenge. Interest-based liquidity tools, such as the interbank market, the discount window and the lender of last resort, are not permissible for Islamic banks, and Islamic liquidity instruments remain slow to develop.”
An IMF study of conventional and Islamic banking systems revealed that the risk of bank disintermediation in jurisdictions with Islamic banks is further heightened by the predominance of retail deposits in bank funding.
“Islamic banks face a specific version of the deposit problem,” adds Kawsar.
“Many structure their current accounts as qard, an interest-free loan from the customer to the bank, which pays no contractual return. If a CBDC also pays no return, customers have one less reason to keep money in those accounts.”